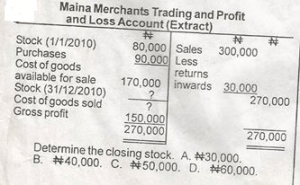
Concept:Closing stock is the excess of current assets over liquid/quick assets.Explanation:Using the current ratio 2:1 with current liabilities of N80,000:Current assets=2×N80,000=N160,000Using the quick ratio 1.25:1:Quick assets=1.25×N80,000=N100,000Therefore:Closing stock=N160,000−N100,000=N60,000Answer:D. N60,000